
Retirement isn’t just about hitting a number it’s about knowing your money will last long enough to fund the life you actually want. That’s where the Retirement Bucket Planner comes in.
Updated July 2026 with Erin Talk new video How to Live Like You Have $2 Million… Without Saving $2 Million, the Retirement Bucket Planner Calculator will let you know if you can retire this way.
Instead of relying on guesswork, outdated rules of thumb, or spreadsheets that only make sense to the person who built them, the bucket approach gives you a clear, visual, and flexible plan for turning your pension and investments into sustainable income.
Whether you’re already retired or planning your exit in the next few years, this framework helps you answer the big question:
“How much can I safely spend each year without running out of money?”
Want a quick way of planning your retirement income? This tool helps you visualise and manage your retirement buckets. Not financial advice.
Inspired by the bucket strategy popularised by financial advisors.Erin Talks MoneyorJames Shackfor more information.
Let’s break it down.
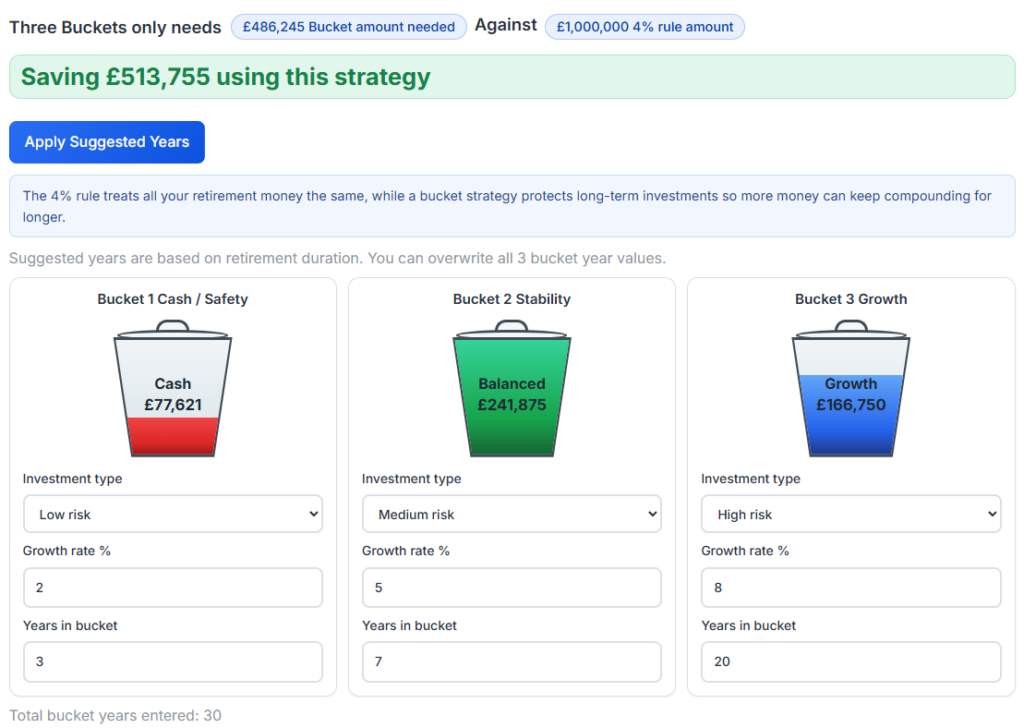
Example of the bucket planner screenshot
Why the Bucket Strategy Works
The bucket method divides your retirement money into three time‑based pots, each with a different purpose and risk level:
1. Short‑Term Bucket (0–5 years)
This is your spending buffer – cash and low‑risk assets that cover your day‑to‑day lifestyle. It protects you from having to sell investments during market downturns.
2. Medium‑Term Bucket (5–15 years)
dThe purpose of the Medium-Term Bucket is to provide growth while gradually reducing risk as the money approaches the time you will need it. Unlike the short-term bucket, which is designed for stability, this bucket should still generate meaningful returns but with less volatility than a 100% equity portfolio.
Many members of the FIRE (Financial Independence, Retire Early) community use this bucket to refill their cash reserve during strong markets while avoiding the need to sell shares after a major downturn.
Typical Asset Allocation
A balanced portfolio might include:
| Asset Class | Typical Allocation | Purpose |
|---|---|---|
| Global Equities | 40–60% | Long-term growth to outpace inflation |
| Investment-Grade Bonds | 20–40% | Reduce volatility and provide reliable income |
| Dividend Equity Funds | 10–20% | Produce a growing income stream |
| Infrastructure / REITs | 0–10% | Diversification and inflation protection |
Views from FIRE Experts
Several well-known FIRE writers and retirement researchers support variations of this approach:
- Michael Kitces argues that a bucket strategy can be psychologically helpful for retirees, although mathematically it is largely equivalent to disciplined portfolio rebalancing. The key benefit is helping retirees avoid panic selling during market downturns.
- Early Retirement Now (Karsten Jeske) emphasizes maintaining a diversified portfolio and keeping sufficient liquid assets to avoid selling equities during severe bear markets. He generally prefers a systematic withdrawal strategy over holding excessively large cash reserves.
- The Escape Artist (UK FIRE) advocates holding several years of spending in low-risk assets so that market volatility does not force unwanted sales of growth investments.
- JL Collins, author of The Simple Path to Wealth, prefers a simpler approach with a largely equity portfolio and selling shares as required. He argues that very large cash allocations can reduce long-term returns, though he acknowledges that some retirees value the peace of mind provided by a cash buffer.
- The Retirement Manifesto (Fritz Gilbert) is a strong supporter of the bucket strategy, using separate cash, income, and growth buckets to make retirement spending easier to manage emotionally and practically.
3. Long‑Term Bucket (15+ years)
This is where your growth engine lives equities and long‑term investments designed to outpace inflation and support spending later in life.
By separating your money this way, you:
- Reduce the emotional stress of market swings
- Avoid panic‑selling during downturns
- Create a natural, rules‑based withdrawal system
- Make your retirement income more predictable
It’s simple, but incredibly effective.
Or if you want to try the full Retirement Planner
How the Retirement Bucket Planner Helps
The FIJourney Bucket Planner turns this concept into a practical, interactive tool that shows:
- How much you can safely withdraw each year
- How long each bucket will last
- When and how buckets should be refilled
- The impact of inflation and investment returns
- How your spending evolves over time
Instead of staring at a spreadsheet wondering if you’ve missed something, the planner gives you:
✔ Clear visuals
Charts that show your bucket levels year by year.
✔ Scenario modelling
Adjust spending, returns, inflation, and see the impact instantly.
✔ Confidence in your plan
You can retire knowing your money is structured to last.
Who This Planner Is For
The Retirement Bucket Planner is ideal if you:
- Are approaching retirement and want clarity on spending
- Have multiple pensions, ISAs, or investment accounts
- Prefer a structured, rules‑based withdrawal method
- Want to avoid the “sequence of returns” risk
- Like seeing your plan visually rather than buried in formulas
It’s especially useful for UK FIRE households who need to coordinate:
- Defined contribution pensions
- ISAs
- Cash reserves
- Tax‑free lump sums
- Flexible drawdown strategies
Why Buckets Beat the 4% Rule
The 4% rule is simple, but it’s also:
- Based on US data
- Not tailored to UK tax rules
- Blind to market conditions
- Static, not dynamic
The bucket method adapts to real life.
When markets fall, you spend from your short‑term bucket. When markets rise, you refill it.
It’s a dynamic, real‑world system that works with volatility instead of pretending it doesn’t exist.
A More Confident Retirement Starts With a Better Plan
Retirement shouldn’t feel like walking a tightrope. With the bucket strategy and the FIJourney planner that brings it to life you get a clear, flexible roadmap for turning your savings into sustainable income.
You’ll know:
- What you can safely spend
- How long your money will last
- When to refill each bucket
- How to adapt to market changes
- How to protect your lifestyle
It’s retirement planning made simple, visual, and stress‑free.