
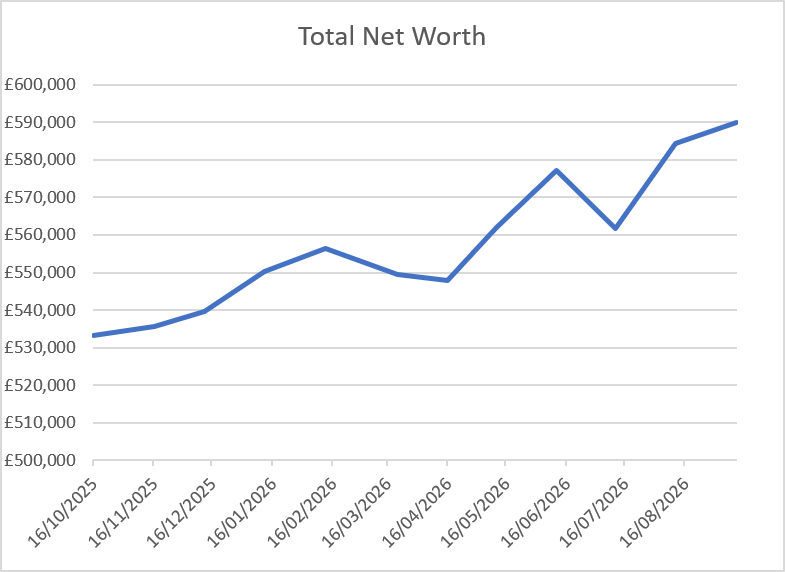
Small increase in shares this month of £5,494 of that £2,500 was from aggressive investments into my AVC.
Is Andy Burnham Autumn Budget coming for you soon?
My Pending Retirement
Am looking at my SIPP, ISA and AVC and seeing that I need to protect the portfolio and allocate into the 3 Buckets strategy.
1. My portfolio risk profile
The most important figures are: 83% net equity / 9% bonds / 7% cash / 1% other.
| Asset exposure | Long | Short | Net |
|---|---|---|---|
| Stocks | 98.20% | 15.03% | 83.17% |
| Bonds | 9.01% | 0.05% | 8.97% |
| Cash | 26.89% | 19.71% | 7.18% |
| Other | 0.78% | 0.10% | 0.68% |
| Total net exposure | 100.00% |
2. The geographical diversification is quite good
My equity exposure is:
| Country/region | % |
|---|---|
| United States | 40.67% |
| United Kingdom | 15.79% |
| Japan | 4.54% |
| Emerging 4 Tigers | 7.56% |
| Eurozone | 14.55% |
This is not a US-dominated portfolio in the way an S&P 500-heavy portfolio would be.
3. The sector exposure is interesting
| Sector | % of equities |
|---|---|
| Financial Services | 24.20% |
| Technology | 20.17% |
| Industrials | 10.92% |
| Energy | 8.81% |
| Healthcare | 8.07% |
| Communication Services | 7.09% |
| Consumer Cyclical | 6.07% |
| Consumer Defensive | 4.89% |
| Basic Materials | 4.98% |
| Utilities | 2.03% |
| Real Estate | 1.48% |
I therefore have a large value/financials component, which is consistent with my interest in RAFI/value strategies.
4. My biggest individual funds
| Holding | Portfolio % |
|---|---|
| VanEck Morningstar Developed Markets Dividend Leaders | 14.01% |
| Orbis Global Balanced | 13.47% |
| Jupiter Merian Global Equity Absolute Return | 13.00% |
| Artemis SmartGARP UK Equity | 12.53% |
| Artemis Global Income | 11.71% |
| Vanguard S&P 500 | 10.86% |
| L&G Global Technology | 9.45% |
| Man Dynamic Income | 5.00% |
| UBS FTSE RAFI Developed 1000 | 4.78% |
| YFS Argonaut Flexible | 4.65% |
The top 10 therefore make up roughly 99.5% of the portfolio, so this looks like essentially complete portfolio rather than a partial holding list.
5. Bucket 2
I currently have:
- Orbis 13.47%
- Jupiter Absolute Return 13.00%
Together that’s approximately:
26.47% of the whole portfolio
And those are two of the funds you’ve been using for my defensive/SORR bucket.
My portfolio therefore already contains a substantial amount of non-equity/less-correlated exposure, even though the headline net equity exposure is 83%.
The Morningstar figures also show:
- Fixed-income effective maturity: 2.90 years
- Duration: 1.87 years
- Average credit quality: B
That last figure is worth paying attention to: the fixed-income component isn’t equivalent to a portfolio of high-quality short-dated government bonds.
6. My top 10 underlying stocks are only about 13%
| Stock | Weight |
|---|---|
| NVIDIA | 2.16% |
| Apple | 2.05% |
| Microsoft | 1.64% |
| Shell | 1.41% |
| HSBC | 1.13% |
| TSMC | 1.12% |
| NatWest | 0.93% |
| Alphabet | 0.88% |
| Broadcom | 0.79% |
| Meta | 0.74% |
| Total | 12.85% |
I have exposure to the big US technology companies, but my overall portfolio isn’t dominated by them.
7. What this means for my retirement buckets
Bucket 1 = cash, Bucket 2 = defensive, Bucket 3 = equities
It looks like every pound in Bucket 2 or Bucket 3 has the same risk.
My actual portfolio has a lot of overlap.
For example:
- Orbis contains equities, bonds, cash and other assets.
- Jupiter uses long/short equity exposure.
- Artemis Global Income has mixed exposure.
- Man Dynamic Income has mixed exposure.
- VanEck Dividend Leaders is still equity.
- UBS RAFI is equity.
- S&P 500 is equity.
- L&G Technology is equity.
My main focus is SORR test, I don’t want a stock market collapse to ruin my retirement
Is the Tax Free Cash going
Reading the article from This is Money it looks like this will not be raided this year as this was unpopular with Rachel Reeves
Rumours that Ms Reeves was plotting an attack on the tax-free lump sum proved particularly damaging ahead of her Budgets as savers rushed to withdraw money from their retirement pots.
So we are safe for now, but I have already taken out £100K of TFC and added to my and the wife’s ISA’s, with both sit at £40,000 each.
Personal allowance to rise
Personal allowance to rise to
The personal allowance could get its first boost in five years, the government is said to be considering raising the income threshold at which earners start paying tax from £12,570 to £15,570 says Sky News
- The standard Personal Allowance is £12,570 for 2026/27.
- It is currently legislated to remain at £12,570 through 2030/31.
- The full new State Pension is already approaching the Personal Allowance, and from April 2027 it is expected to exceed £12,570.
- The State Pension is taxable income, even though DWP does not deduct the tax before paying it.
- However, the government has said that people whose only income is the State Pension will not be required to pay the small amount of tax through Simple Assessment from 2027/28. The detailed mechanism is still being worked out.
Net Worth September 2026
| Date | Total Net Worth | £ Gain this month | % Gain this month |
| 16/10/2025 | £533,165 | £22,647 | 4.44% |
| 16/11/2025 | £535,587 | £5,591 | 1.05% |
| 12/12/2025 | £539,739 | £4,152 | 1.40% |
| 12/01/2026 | £550,380 | £10,641 | 1.97% |
| 12/02/2026 | £556,319 | £5,939 | 1.08% |
| 21/03/2026 | £549,551 | -£10,130 | -1.81% |
| 16/04/2026 | £547,917 | -£1,634 | -0.30% |
| 11/05/2026 | £562,081 | £15,241 | 2.79% |
| 11/06/2026 | £577,240 | £15,159 | 2.70% |
| 11/07/2026 | £561,815 | -£15,425 | -2.67% |
| 11/08/2026 | £584,401 | £22,500 | 4.00% |
| 11/09/2026 | £589,896 | £5,495 | 0.94% |
| Yearly | £80,176 | 15.59% |
Retirement Calculators
I’m about to review the major free and paid retirement calculators on the market, and I want to be upfront about where I’m coming from. I built my own retirement calculator it’s free, I don’t sell it, and I have no commercial stake in steering you toward it. If anything, the real motivation behind this review is selfish: I want to see how my own numbers stack up against everyone else’s.
A bit of background on that calculator. I built it with an AI co-pilot, and I didn’t write a single line of code myself. But don’t let that fool you into thinking it was quick or easy. It took about two months of genuine work testing, reworking, testing again, and recruiting volunteers from Reddit and Facebook to stress-test it against real scenarios. If you’ve bought into the idea that AI can just “build it for you” in an afternoon, I’d push back hard on that. You still have to manage the project the way a developer would: test relentlessly, catch what’s broken, refine it, and bring in outside eyes before you trust the output.
I don’t believe in the 4% rule
One thing that will shape how I judge every calculator in this review: I don’t rate the 4% rule very highly. It’s fine as a rough, finger-in-the-air estimate, but it falls apart as a serious planning tool.
Instead, I build my numbers around the 3 Bucket Strategy factoring in compounding growth, applying a conservative 5% growth rate, and keeping 2–3 years of cash in reserve. That cash buffer isn’t an afterthought bolted onto the plan; it’s built into how the bucket structure works from the start.
Finally Making Time for Art
I recently picked up around 100 art books from a school library enough to keep me occupied for a good long while. Art has always been a genuine love of mine, mostly through looking at the work itself and digging into the history and story behind it.
I sometimes wish I’d been more cultured earlier in life, but work and family had other plans. There wasn’t much room for hobbies beyond a bit of fishing and building websites part-time mostly just getting through the years. Now, finally, there’s a bit more space to indulge it properly.
Your point that every pound in buckets 2 and 3 carries similar risk is the key finding. There’s a simple way to test it before you retire: pull the monthly returns for Orbis Global Balanced and the Jupiter absolute return fund, and look only at the months when global equities fell more than about 3%. A fund can have a modest correlation to equities overall and still fall alongside them in exactly those months, and those are the only months a sequence-of-returns bucket is for. The B average credit quality you spotted points the same way: high-yield bonds tend to behave like equities in a sell-off, so a slice of plain short-dated gilts or cash might do more for bucket 2 than it looks on paper.